Featured Articles
  • The World’s Top 100 Electronic Connector Manufacturers 

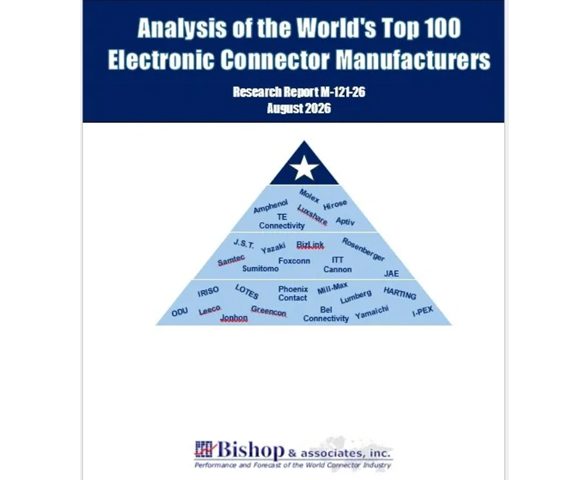
    In 2025, the world’s top 100 connector manufacturers generated $81.386 billion in shipments, representing 82.1% of the total worldwide connector market—up from 81.0% in 2024. A new Bishop & Associates report identifies these companies and analyzes their activities, performance, products, and expertise. Bishop & Associates new 10-chapter research report provides a comprehensive analysis of theRead More

  • Global Connector Market Posts 14.7% Growth in 2025, Led by Asia Pacific Surge

    New research from Bishop & Associates tracks more than $12.7 billion in market expansion, with huge growth in Asia. Learn what markets topped the charts. The worldwide electronic connector market expanded by more than $12.7 billion in 2025, delivering a 14.7% increase over 2024 sales, one of the industry’s stronger performances in recent years. AllRead More

Facts & Figures

To Web or Not to Web?

November 2013 – How important are websites in the B2B arena? We asked European connector customers if, how, and when they use the Internet for business purposes, and they shared their experiences for a snapshot of the connector industry online.
Big Data Survey Reveals More Tricks Than Treats

Big Data Survey Reveals More Tricks Than Treats Companies investing in Big Data initiatives are waiting 18 to 24 months to see return on their investments (ROI) and only 3% give their enterprise information “Superman” status, according to a recent Halloween-themed survey. The alarming gap in anticipated ROI versus reality is just one horror revealedRead More

Chip-Level Optical Interconnect Market Could Generate $520 Million by 2019

Chip-Level Optical Interconnect Market Could Generate $520 Million by 2019 Research and Markets has released “Revenue Opportunities for Optical Interconnects: Market and Technology Forecast – 2013 to 2020 Vol II: On-Chip and Chip-to-Chip.” According to the report, the addressable market for chip-level optical interconnects could eventually run into billions of units and revenues in thisRead More

Connector Industry Profitability for 2013

October 2013 – Year 2009 was a perfect storm of profit killers, but in 2010, the industry experienced a complete reversal of misfortune. If history is a guide, what does that mean for 2013? Profitability is excellent!

The Impact of Positive Train Control

October 2013 – Significant progress toward implementing PTC is being made as US railroads collaborate with federal regulators and suppliers in order to meet a 2015 deadline enacted by the US Rail Safety Improvement Act of 2008.

Instrumentation Suffers Soft Semi Sales

October 2013 – The combined annual revenue of all the market sectors tracked was $4.3 trillion in 2012, an increase of 4.9% over 2011. Of the 13 market sectors, instrumentation was the third-fastest growing market sector in 2012, at 5.4% year-over-year with combined revenues of $29 billion. Profitability was $3.5 billion at 12.1% of sales.

Mirror, Mirror on the Wall – Top 10 Best Performers

October 2013 – Does the list of Top 10 connector manufacturers for quality diverge from the Top 10 list based on price? Do customers make buying decisions based on price or quality (or both)? Bishop & Associates asked customers to rank European connector companies and compared the two lists to find out.


The Auto Industry – Hitting on All Cylinders

September 2013 – In the automotive connector market, the Top 10 manufacturers of connectors used in automotive applications account for 94% of sales. This is primarily because the large tier one and tier two OEMs purchase from connector companies that offer broad product offerings, leading-edge technology, and significant value-added programs.

Monthly Summary of Industry Trends: July Sales Second-Best in 2013

The connector industry has been in a soft-demand environment since October 2011. We now have recorded 22 consecutive months in which orders and sales have achieved small, single-digit year-over-year gains or losses. However, July YOY sales growth of +4.8% is encouraging and may signal a better second half of 2013.

An Industry Under Siege: How Much Defense is Enough?

September 2013 – In 2013, governments and defense agencies — from the US to China to the euro zone — are being asked to justify defense spending against a broad range of domestic priorities. Domestic demands for austerity and social investment are eroding previous commitment to high levels of defense spending by many nations. Defense is still the first priority of many governments; however, it is becoming more difficult for the armed services and industry to plan in this budgetary environment.

The Robotic Age is Here – Industrial Robot Market Statistics

September 2013 – Industrial robots are a common sight on the factory floor, particularly in automotive markets. They offer high-precision handling and speed, and reduce operator risk, such as worker exposure to hazardous materials, and to production dangers in general. In the near future, industrial robots will include those that cooperate with humans, instead of replacing them. This will open up new potential for utilizing robots in factories and in the agricultural market, as well as for domestic purposes.

Heavy Industry Drives the Industrial Market

September 2013 – Year-over-year heavy duty transportation market sales growth slowed substantially starting in 4Q11 and has been negative in 1Q13 and 2Q13, while sequentially, 2Q13 sales increased 3.8% vs 1Q13.

Analysis of the World’s Top 100 Electronic Connector Manufacturers
x